

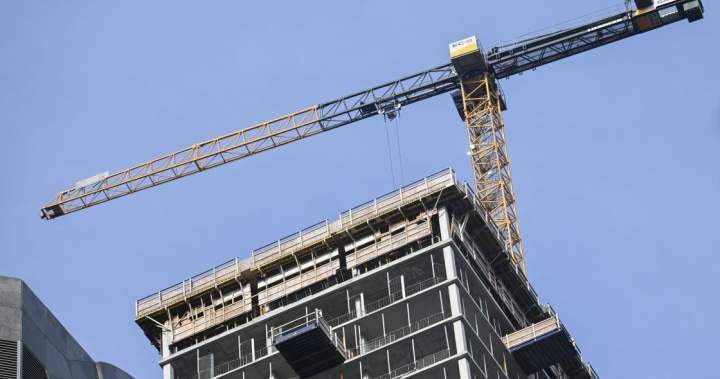
Housing affordability continues to be a key issue for millions of Canadians, and a new report suggests specific policy changes could help many first-time home buyers get into home ownership.
The National Housing and Investment Initiative, a collaboration of members from some of Canada’s biggest banks and real estate groups, released its November report with several recommendations for what it says can help create a more sustainable housing market.
This comes as sales dwindle in some of Canada’s biggest markets, like Toronto, as prices remain high and available supply is falling behind demand.
But some experts are skeptical about the report’s proposed potential benefits outweighing the risks for the housing market and overall affordability.
“We have to ask, are there any risks coming from these recommendations that could undermine the other factors that are happening right now to put a downward pressure on home values, which is what we want to restore affordability over the medium and long term,” says Paul Kershaw, policy professor at the University of British Columbia and the founder of the advocacy think tank Generation Squeeze.
“Even if we implement most or all of these recommendations, we’re still not talking about restoring housing affordability throughout our housing market, our housing system for many, many years.”
These are the recommendations outlined in the report.
One of the report’s recommendations is to make it easier for young Canadian first-time home buyers to afford a down payment on newly constructed homes. This includes both by lowering the required down payment for first-time buyers and establishing an assistance program, like a low-interest loan, to help these potential buyers afford their down payment.
But making it easier for buyers to get into the housing market without increasing supply simultaneously can risk higher prices for homes in the long term.
Get daily National news
Get daily Canada news delivered to your inbox so you’ll never miss the day’s top stories.
The report says that by limiting these financial supports to new homes, it will avoid inflating the resale market.
“There’s a worry right now that we’re not getting enough of those newly built homes because there isn’t enough demand for them at their current price points,” says Kershaw.
“It worries me that that does risk refueling the housing market more generally, but because it is being honed in specifically on new builds, it might be the kind of thing that’s just like walking the tightrope carefully enough that it’s going to help us get more supply without over-fueling the inflation of the market more generally.”
Once a home-buyer has enough money for a down payment, they likely will still need a mortgage to finance the remaining balance on that home.
The report recommends refining mortgage stress tests — which require buyers to qualify at a higher mortgage rate than they may initially get — to allow for more nuance and flexibility.
For example, introducing a sliding qualifying rate based on the term of the mortgage or the type of buyer, and offering lower qualifying rates for both new builds and first-time buyers in general.
“Easing the stress test a little bit certainly allows first-time buyers to afford a little more,” says John Pasalis, real estate broker and president of Move Smartly Realty.
“In particular, if they’re going to relax it, for example, for new housing, it kind of makes it a little bit more affordable, drives more supply and kind of pushes buyers more into that market — that’s the segment that’s struggling.”
The report also recommends young Canadians and first-time buyers be able to write off some of their mortgage interest on newly built homes so they can more easily afford them. However, that tax break would be balanced by reducing the capital-gains tax exemption on primary residences if they sell and make a profit.
Builders have largely pulled back on construction plans in recent years mainly because of a combination of higher costs to build and a lack of private investment.
The report cites an RBC study from last year, which estimates Canada’s real estate market needs about $2 trillion of capital deployment over the next five years to meet the current need for affordable housing, which is about 3.5 million homes.
With condo construction, developers usually have to wait to sell the majority of units before building can commence, and although federal incentives are available for new construction, it is mainly geared towards purpose-built rentals and houses.
“If they only need to pre-sale 40 per cent of the units, that changes so much for them,” says Pasalis.
“They can build a lot faster. They can start building units that they believe the end user market needs upon completion rather than just waiting for investors to buy them.”
To entice the private sector into building more housing, the report calls for expanding federal financing measures to include qualifying condo projects, speeding up project approvals both at the federal and municipal level, and adjusting the foreign buyers’ ban to allow for more international investors.
The federal foreign home buyers ban expires on Jan. 1, 2027, and Budget 2026 proposed extending this for two years but would also except newly built homes from the ban.
The report also recommends maintaining sustainable and predictable immigration targets and reforms that are conducive to growing the housing market.
High immigration levels can add to overall housing demand, which can lead to higher prices. At the same time, the report says that focused immigration policies can help ensure builders have enough of the skilled workers they need to get these projects built efficiently.
Finally, the report says that keeping accurate and consistent housing sector data is key to tracking progress, keeping all sides accountable and creating more predictability for both builders and buyers.
– with a file from Global’s Jacqueline Hansen
© 2026 Global News, a division of Corus Entertainment Inc.
Read the full article here